
Executive Overview
Agricultural technology stands at a historic crossroads. From the sprawling row crops of the American Midwest to the intricate specialty orchards of Europe and California, automation has shifted from a futuristic concept to a fundamental operational strategy. Whether it is precision planting, targeted weeding, high-resolution scouting, or localized crop spraying, agricultural robotics remains one of the most resilient and dynamic sectors within agtech innovation.
Major original equipment manufacturers (OEMs)—including legacy giants such as John Deere and AGCO—are aggressively anchoring their multi-year growth strategies in advanced research, artificial intelligence, and field-ready robotics. This structural evolution is comprehensively mapped in the newly released 2026 Crop Robotics Landscape report published by strategic consulting firm The Mixing Bowl.
Published biennially since 2022, The Mixing Bowl’s report serves as the definitive census of the global agtech robotics space. The 2026 edition highlights an ecosystem in a state of fierce churn: the directory now encompasses 400 global companies, representing a robust 25% expansion in total mapped entities compared to the 2024 index. Beneath this surface-level growth, however, lies a deeper narrative of industrial maturation. A staggering 36% of the 2026 cohort consists of brand-new market entrants, while 20% of the companies tracked in the previous iteration have quietly exited the field through closures, pivots, or acquisitions.
This volatile turbulence is not a sign of failure, industry experts argue, but rather the classic birth pangs of a maturing market. As venture capital funding normalizes away from the intoxicating peaks of the early agtech hype cycle, the sector is shedding speculative excess in favor of hard-nosed commercial viability. This comprehensive analysis explores the shifting geographical hubs of agtech innovation, the state of technological adoption across categories, the myth of the "lights-out" fully automated farm, and what lower venture capital inflows truly mean for the future of farming.
Detailed Chronology and Industry Evolution
To understand the current state of crop robotics in 2026, it is vital to trace the trajectory of how the sector has evolved over the past decade. The journey from rudimentary GPS-guided tractors to autonomous, multi-modal machine fleets highlights a rapid acceleration in artificial intelligence, computer vision, and mechanical engineering.
The Genesis of Precision Ag (Pre-2022)
Long before autonomous field robots became commonplace, precision agriculture was largely defined by autosteer systems and variable-rate fertilizer applications. During this era, innovation was heavily concentrated within major machinery manufacturers. Retrofit kits began entering the market, allowing farmers to upgrade existing iron with spatial awareness tools. However, these systems relied heavily on human operators behind the wheel; the machinery was smart, but it was far from autonomous.
The Hype Cycle and Pandemic Acceleration (2022–2024)
When The Mixing Bowl published its inaugural crop robotics landscape report in 2022, the world was emerging from pandemic-driven supply chain crises and labor shortages. This period catalyzed a gold rush of venture capital into agtech. Start-ups promised autonomous solutions for virtually every manual bottleneck on the farm, from fruit-picking robotic arms to laser-weeding laser platforms.
By 2024, the landscape had swelled as venture dollars chased novel hardware concepts. Yet, the realities of agricultural economics began to set in. Farm margins tightened, hardware manufacturing proved brutally expensive, and software-as-a-service (SaaS) models did not easily translate to heavy industrial machinery operating in hostile, unpredictable outdoor environments.
The Maturation and Market Shakeout (2024–2026)
The latest 2026 landscape report captures a market entering adolescence. The two-year window between 2024 and 2026 witnessed a profound Darwinian sorting process. While 400 global companies are currently tracked—a 25% jump from 2024—the simultaneous 20% exit rate demonstrates that the market is ruthlessly filtering out weak business models.
Companies that survived this ceding process are those that successfully transitioned from proof-of-concept prototypes to reliable, commercial-grade tools that solve immediate labor and input cost pressures for growers. The narrative has shifted away from speculative moonshots toward modularity, durability, and immediate return on investment (ROI).
Supporting Context & Metrics: Breaking Down the 2026 Landscape
The Mixing Bowl’s 2026 report organizes the expansive agricultural robotics universe along two primary axes: functional technology types and crop system categories.
Technological Segmentation
The report segments companies based on their core engineering focus:
- Navigation and Autonomy: Systems enabling unmanned vehicle movement, path planning, and obstacle detection.
- Harvesting Robotics: Complex mechanical arms and computer-vision systems designed to pick delicate specialty crops (e.g., strawberries, apples, grapes).
- Smart Spraying Systems: AI-driven spot-spraying technologies that identify weeds or crop diseases in real-time to minimize chemical usage.
- Robotic Platforms and Carriers: Multipurpose utility vehicles designed to pull or carry various implements across fields throughout the crop cycle.
Crop System Specialization
Robotic utility varies wildly depending on the biology and layout of the crop. The 2026 landscape is divided across four distinct agronomic sectors:
- Row Crops: Corn, soybeans, wheat, and cotton, characterized by broad acreage and high standardization.
- Specialty Crops: High-value fruits and vegetables requiring delicate handling and intensive labor.
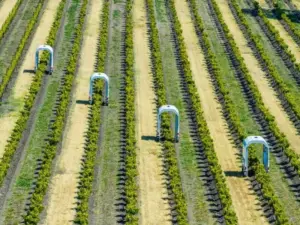
- Permanent Crops: Orchards, vineyards, and tree nuts where perennial maintenance and harvesting demand specialized form factors.
- Indoor Crops: Controlled Environment Agriculture (CEA), greenhouses, and vertical farms where robotics operate in predictable, climate-controlled conditions.
Geographical Distribution and Innovation Hubs
The global footprint of crop robotics reveals striking regional dynamics. According to the 2026 report, European companies account for a full 50% of the global crop robotics landscape, driven by strict regulatory frameworks regarding chemical applications, intense labor shortages, and strong regional public-private research partnerships. Meanwhile, United States-based companies represent 18% of the global total.
Within the United States, California retains its undisputed crown as the epicenter of agtech innovation, housing 40% of all U.S.-based crop robotics companies. However, industry experts caution that geographic proximity to Silicon Valley venture capitalists can sometimes blind start-up founders to the realities of primary agricultural production.
Michael Rose, partner at Better Food Ventures and a key contributor to The Mixing Bowl’s robotics landscape, emphasizes the critical need for spatial proximity to end-users.
"You can’t sit in Silicon Valley and spin up a company and then sell it to the market," Rose asserts. Start-ups must station themselves where the producers live, breathe, and farm to ensure their engineering solves tangible, everyday operational pain points.
Official Statements and Industry Insights
Adoption curves across the agricultural sector are not uniform; they are dictated heavily by technological maturity and risk aversion. Speaking to industry analysts, Michael Rose provided a granular breakdown of where adoption stands today.
The Triumph of Navigation and Autonomy
Navigation and autonomy technologies have decisively won the commercialization race in mainstream agriculture. Unlike niche harvesting solutions, navigation systems enjoy broad, mainstream integration.
"Navigation and autonomy that is well deployed—you look at navigation technology in tractors and combines for row crops, it’s been there a long time and fully deployed, fully commercialized, and broad adoption," Rose noted. "Everybody is playing in that space, either retro kits or units themselves."
Beyond primary vehicle guidance, the 2026 landscape highlights accelerating growth in precision spraying technologies and a robust, expanding pipeline of modular robotic platforms capable of handling multiple seasonal duties.
Debunking the Myth of Full Automation
As tech enthusiasts dream of fully automated agricultural futures, industry leaders are adopting a far more pragmatic tone. Discussions regarding "lights-out" farming—facilities operating entirely without human oversight, akin to advanced manufacturing plants in other industries—are frequently debated among innovators. However, Rose believes this vision fundamentally misunderstands biological systems.
"You’ll have full automation where it makes sense," Rose explained. "Will we see a farm run like a lights-out manufacturing facility that we can see in China, where there are no human beings? I don’t think so."
Instead of replacing the farmer entirely, the future of agriculture points toward a symbiotic hybrid model. Automated systems will shoulder repetitive, dangerous, and labor-intensive tasks (such as night-time spraying or monotonous mechanical weeding), while human expertise will remain vital for strategic management, agronomic decision-making, and machinery oversight.
Interpreting Venture Capital Inflows
A superficial glance at venture capital metrics might cause concern for casual observers. Data from The Mixing Bowl indicates that VC funding remained relatively flat between 2024 and 2026, with listed companies collectively raising $600 million over the two-year period. This represents a clear contraction from the frothy peaks of the prior agtech investment boom.
However, Rose frames this capital cooling not as a crisis, but as a healthy biological indicator of market maturation. In the early phases of an emerging technology sector, speculative venture capital floods in to fund dozens of competing experimental approaches. As the industry matures, venture capital naturally recedes, making room for private equity, strategic corporate acquisitions, and revenue-driven organic growth.
Drawing parallels to historical consumer technology cycles, Rose points out:
"Where’s the role for venture anyway? It was actually a couple years ago. So, did we see this in handset manufacturers? Did we see this in PC hardware? There’s a point where early-stage venture does drop off."
The defining question for the agtech sector is no longer whether investors will fund every bright idea, but rather market capacity: "The question is how many more companies do you need to address the space?"
Future Outlook: The Next Horizon in Crop Robotics
As the agricultural sector moves through the remainder of the decade, several key trends will dictate which crop robotics companies thrive and which join the 20% casualty rate tracked between 2024 and 2026.
1. The Consolidation Wave
With 400 companies currently populating the landscape, market saturation is a growing concern for growers who are hesitant to manage disconnected fleets of single-purpose robots from different vendors. The coming years will likely see major OEMs and well-funded mid-tier agtech firms aggressively acquiring specialized start-ups to build unified, interoperable farm management ecosystems. Farmers do not want ten different tablets for ten different robots; they demand a single dashboard.
2. Regulatory Pressures as Growth Catalysts
Environmental regulations concerning pesticide runoff, carbon footprints, and water usage are tightening globally, particularly in Europe and parts of North America. Smart spraying, mechanical laser weeding, and micro-dosing robotic systems will transition from luxury tools to regulatory compliance necessities. Robots that can drastically cut chemical applications while maintaining crop yields will command massive market premiums.
3. Solving the Specialty Crop Labor Crisis
While row crop autonomy is largely solved through tractor guidance and large-scale implement automation, specialty crops (fruits, vegetables, berries) remain chronically underserved due to the extreme dexterity required for harvesting. Engineering breakthroughs in soft robotics, high-speed machine vision, and edge computing will be the primary battlegrounds for start-ups looking to capture value in high-value perennial and specialty markets.
Conclusion
The 2026 crop robotics landscape confirms that agricultural automation has graduated from the realm of speculative science fiction into hard industrial reality. While venture capital has slowed and market exits have weeded out the unprepared, the sector is stronger, more grounded, and more responsive to real-world farm economics than ever before. By prioritizing hybrid workflows, proving tangible ROI, and anchoring development in real-world agronomy, the crop robotics industry is successfully building the resilient machinery of tomorrow’s food production systems.