
LONDON — The agtech sector is undergoing a profound structural metamorphosis. For over a decade, venture capital and private equity have poured billions of dollars into software dashboards, remote-sensing hardware, and predictive data analytics. The promise was simple: give farmers more data, and they will optimize yields, reduce chemical inputs, and drive sustainability.
However, according to Antony Yousefian, a leading voice in agricultural investment and partner at venture firm The First Thirty, that era is drawing to a close.
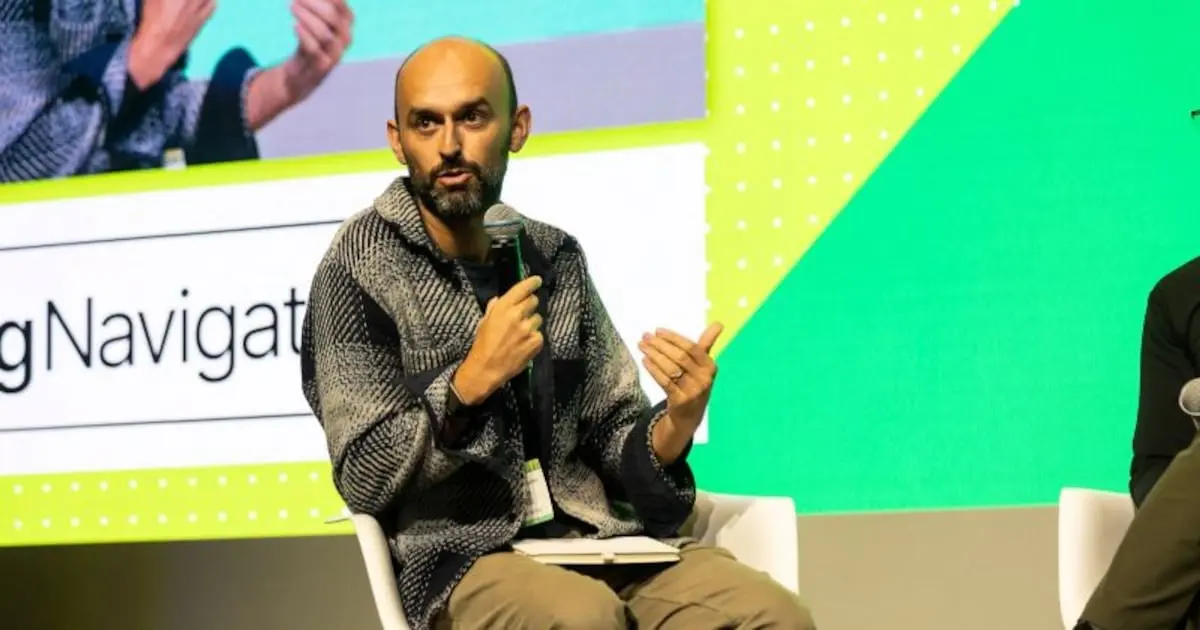
Speaking exclusively to AgNavigator at the World Agri-Tech Innovation Summit in London, Yousefian argued that the market has grown weary of mere insights. Investors and buyers alike are no longer satisfied with platforms that tell growers what is happening; they want businesses that take ultimate financial and operational responsibility for the results.
This paradigm shift—moving from passive software dashboards to active, risk-sharing "outcomes-as-a-service" models—is poised to disrupt traditional agricultural supply chains. Simultaneously, forward-thinking investors are looking beyond the traditional farm gate, aligning their capital with the rising "agri-health" movement. By linking soil biology directly to human nutrition and chronic disease prevention, the agtech industry is positioning itself not just as a branch of food production, but as an indispensable pillar of preventative healthcare.
Executive Overview
The global agricultural technology sector stands at a critical juncture. Faced with macroeconomic volatility, restructuring across major agricultural inputs, and persistent questions surrounding profitability, start-ups are being forced to evolve.
Key developments driving this transformation include:
- The Death of the Dashboard: Agtech business models are transitioning from software-as-a-service (SaaS) data providers to outcome-based underwriters that share financial risk with farmers.
- Vertical Integration: Nimble start-ups are moving further down the value chain, increasingly competing with legacy seed, genetics, and agronomy giants by establishing direct-to-consumer brands.
- The Rise of Agri-Health: Investors are recalibrating valuations around human health outcomes, treating food not as a bulk commodity, but as the world’s most accessible form of preventative medicine.
- Biological Intelligence: A convergence of low-cost sensors, genomics, and artificial intelligence (AI) is unlocking unprecedented transparency across the entire food supply chain—from microbe to meal.
Detailed Chronology: The Evolution of AgTech Investment
To understand where agricultural technology is heading, it is necessary to examine how the sector arrived at this crossroads.
Phase 1: The Digitization of the Farm (2010–2018)
In the wake of the 2008 financial crisis and the subsequent boom in venture capital, agtech emerged as a darling of impact and deep-tech investors. The initial wave focused heavily on hardware and foundational software. Drones, satellite imagery, soil probes, and yield-mapping software flooded the market. The core value proposition was digitization: taking analog farming practices and converting them into bits and bytes.
Phase 2: The SaaS Saturation and Friction (2019–2023)
As the market matured, farm-level software fatigue set in. Farmers were inundated with disparate dashboards from dozens of competing vendors, each requiring subscription fees but rarely offering a guarantee of return on investment. Adoption rates stalled among growers who questioned why they should pay for software insights while shouldering 100% of the operational and financial risk of executing them. Venture capitalists began noticing diminishing returns on pure-play SaaS models.
Phase 3: The Outcome-Based Era and Agri-Health Integration (2024–Present)
Today, the industry is entering its most ambitious phase yet. Investors like The First Thirty are pioneering models where technology providers underwrite operational decisions. If an agtech platform recommends a specific biological intervention, it must stand behind the financial result. Concurrently, the realization that soil health directly dictates nutritional density has bridged the gap between agriculture and human wellness, sparking the "agri-health" thesis.
Supporting Context & Metrics: Redefining Value Creation
The fundamental friction of traditional agtech has always been the disconnect between information and execution. A sensing company could identify a nitrogen deficiency, but the farmer still had to buy the fertilizer, apply it correctly, and hope weather patterns cooperated.
Yousefian highlights how the modern start-up is collapsing this chain:
"A sensing company was present before offering a dashboard and insights. Now we’re seeing businesses saying: ‘You should do this and I will underwrite that intervention decision.’"
Moving Down the Value Chain
By underwriting interventions, agtech start-ups naturally encroach upon territories traditionally guarded by legacy agricultural conglomerates. Companies that began as software or sensing platforms are evolving into comprehensive agronomy firms, boutique seed providers, and specialized genetics brands.
Consolidation across the agricultural input sector has left structural vacuums in the market. Ambitious start-ups are stepping into these voids not as software vendors, but as vertically integrated market players that own the customer outcome from end to end.
The Economics of Agri-Health
The economic logic underpinning the agri-health thesis rests on the staggering global costs of chronic lifestyle diseases. Healthcare systems are buckling under the weight of conditions linked directly to poor nutrition and ultra-processed diets.
By investing in companies that measure and optimize nutrient density—such as Edacious, a portfolio company of The First Thirty—investors are laying down the digital and biological infrastructure required to verify food quality. When consumers begin asking not just “What is in my food?” but “What did my food eat?”, transparent supply chains will command massive pricing power.
Official Statements and Industry Insights
Antony Yousefian’s remarks at the World Agri-Tech Innovation Summit in London captured the pragmatic optimism currently driving forward-thinking venture funds:
- On Business Models: "We’re seeing more ambition around outcomes as a business model. We’re seeing start-ups talking about delivering outcomes as a service."
- On Disrupting Incumbents: "I think agtechs have an opportunity to almost compete with their customers. Become an agronomy company, become a seed business. A genetics business can become a brand."
- On Food as Medicine: "The cheapest form of healthcare is the food that you eat. We see agriculture and food businesses becoming preventative healthcare businesses."
- On Biological Intelligence: "What is missing is the data. What I’m very excited about is a combination of sensing, genetics and AI. We call this biological intelligence."
- On Capital and Planet Health: "We see signals that this time is different. If people can see they can make money from improving soil, we’ll have a better planet."
Future Outlook: The Intersection of AI, Biology, and Capital
Looking ahead, the successful agtech enterprises of the late 2020s and 2030s will not look like traditional tech companies, nor will they resemble traditional farming cooperatives. They will operate as data-driven biological networks.
The Power of "Biological Intelligence"
The convergence of generative AI, falling costs for genomic sequencing, and advanced low-cost agricultural sensors is making it possible to decode complex biological interactions in real time. Yousefian defines this fusion as biological intelligence—the missing link that allows companies to trace human wellbeing directly back to the microbial health of farm soils.
Autonomous machinery and precision application systems will execute these biological interventions at a scale and cost previously thought impossible, dramatically lowering the barrier to entry for outcome-based farming.
Overcoming Capital Hurdles
While capital deployment remains a persistent hurdle in the capital-intensive agricultural sector, shifting investor priorities provide a powerful tailwind. As institutional investors face mounting pressure to demonstrate both financial returns and verifiable environmental, social, and governance (ESG) impacts, the soil-to-health narrative offers a compelling dual-purpose thesis.
By proving that regenerating soil health generates direct financial yields while simultaneously improving public health, the agtech sector is finally unlocking the capital it needs to scale globally.
About the Upcoming Event
This analysis builds upon discussions conducted at the World Agri-Tech Innovation Summit in London. The full, on-camera interview with Antony Yousefian, alongside insights from other global industry leaders, will be featured in AgNavigator’s upcoming World Agri-Tech Unwrapped webinar on November 4. The session will be accessible live and on demand. Free registration details can be found through AgNavigator’s official event portal.