
Executive Overview
Bayer AG’s Crop Science division faced a challenging third quarter, marked by a contraction in core agricultural input sales as a combination of severe meteorological anomalies, intensifying generic competition, and strict regulatory frameworks weighed on global performance. According to the company’s latest financial disclosures, overall division sales dipped by 2% during the quarter. While the seeds and traits portfolio demonstrated resilience and continued innovation-led growth, the crop protection segment bore the brunt of macroeconomic and environmental headwinds, particularly across Europe, the Middle East, and Africa (EMEA), as well as key Asian markets.
Executives, including Chief Executive Bill Anderson and Chief Financial Officer Judith Hartmann, pointed to a convergence of compounding factors: a historic European drought, El Niño-related climatic shifts, ongoing regulatory restrictions, and active portfolio pruning. These pressures led to a 6% year-over-year decline in core crop protection sales for both the third quarter and the year-to-date period. Fungicide and herbicide applications plummeted as dry, scorching conditions curtailed standard seasonal spraying windows, while glyphosate revenues fell by 5%.
Despite these EMEA and Asian hurdles, Bayer’s agricultural portfolio found a vital engine for growth in Latin America. Bolstered by an exceptionally strong start to the seasonal cycle, Latin American markets fueled a 3% expansion in global seeds and traits sales for the quarter, anchored by robust soybean performance. Furthermore, rigorous cost-cutting initiatives, portfolio optimization, and the ongoing execution of Bayer’s multi-year restructuring strategy helped buffer the division’s profitability. On a year-to-date basis, Crop Science sales advanced by 3.6%, with EBITDA before special items surging 17.4% and the division’s EBITDA margin holding firm at 24.6%.
As the agricultural sector looks toward 2027, Bayer remains cautiously optimistic. While structural challenges—ranging from farmer profitability to aggressive generic pricing—persist, the company’s leadership maintains that its long-term turnaround strategy remains firmly on track, balancing operational discipline in mature markets with high-margin expansion in the Global South.
Detailed Chronology: Q3 Performance and Operational Dynamics
The Anatomy of a Challenging Quarter
The third quarter of 2026 exposed the deep vulnerabilities of traditional crop protection models when subjected to concurrent environmental and regulatory shocks. Throughout July, August, and September, Bayer’s agricultural operations had to adapt to rapidly deteriorating conditions across the Northern Hemisphere.
In Europe, the cumulative impact of historic multi-year droughts severely depleted soil moisture, altering typical farming calendars and directly suppressing the demand for agricultural chemicals. Crop Science President Rodrigo Santos noted during the quarterly analyst call that unseasonably hot and dry weather across large swaths of Europe and Asia dramatically reduced the incidence of fungal pathogens, rendering preventative fungicide applications largely unnecessary. Consequently, fungicide volumes contracted sharply, dragging down the broader crop protection metrics.
At the same time, regulatory pressures continued to reshape Bayer’s addressable market. The phasing out of certain active ingredients in European jurisdictions, combined with deliberate corporate portfolio exits designed to streamline operations and phase out lower-margin products, further depressed top-line figures. These deliberate strategic contractions, compounded by an influx of low-cost generic alternatives encroaching on established markets, created a hostile pricing environment for Bayer’s flagship herbicide and insecticide lines. Glyphosate sales alone dropped 5% globally during the quarter, driven primarily by the EMEA region, where regulatory headwinds and generic displacement converged.
The Latin American Counterweight
While the agricultural landscape in the Northern Hemisphere remained depressed, Latin America emerged as a beacon of vitality for Bayer’s operations. The region kicked off its agricultural season with robust momentum, driven by favorable early planting conditions and strong demand for advanced agronomic technologies.
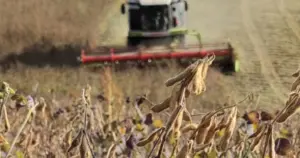
Bayer’s seeds and traits business capitalized directly on this regional dynamism. Global soybean sales within the portfolio rose 5% in the third quarter alone, pushing year-to-date growth for the crop to an impressive 45% (or 10% when excluding licensing-related income). Corn performance remained equally steady, posting flat results for the quarter but achieving a solid 4% increase across the first nine months of the fiscal year.
Chief Financial Officer Judith Hartmann emphasized that targeted commercial actions and disciplined supply chain management allowed Bayer to capture maximum value from the Latin American surge, offsetting losses sustained in drought-stricken markets elsewhere.
Supporting Context & Metrics: Financial Health and Segment Analysis
To properly evaluate Bayer’s Q3 performance, analysts must look beyond the top-line contraction in crop protection and examine the broader structural health of the Crop Science division. The numbers reveal a tale of two distinct asset classes: legacy chemical inputs facing structural attrition versus proprietary biotechnologies enjoying secular growth.
Financial Performance Breakdown
- Overall Division Sales: Declined by 2% in Q3 due to headwinds in crop protection.
- Year-to-Date Crop Science Sales: Up 3.6%, demonstrating underlying resilience over the broader nine-month reporting period.
- Core Crop Protection Sales: Fell 6% in Q3 and remained down 6% on a year-to-date basis.
- Glyphosate Revenues: Decreased by 5% in the third quarter, heavily impacted by market dynamics in EMEA.
- Seeds & Traits Performance: Rose 3% in Q3, fueled by a 5% jump in global soybean sales and stable corn demand. Year-to-date soybean sales surged 45% (10% ex-licensing).
- Profitability Margins: Division EBITDA margin reached 24.6% for the year-to-date period.
- EBITDA Before Special Items: Increased by 17.4% for the first nine months of 2026, driven by operational efficiencies and restructuring execution.
The Structural Divide: Innovation vs. Commoditization
The financial metrics underscore a widening strategic divide within the global agricultural input sector. On one side, crop protection has transformed into a high-friction battleground. Farmers facing tighter margins and elevated borrowing costs are increasingly turning to generic alternatives to protect their bottom lines. Regulatory restrictions further erode the profit margins of proprietary formulations by forcing expensive compliance re-evaluations or outright withdrawals.
Conversely, the seeds and traits business functions as an innovation-driven stronghold. Farmers demonstrate a clear willingness to pay premium prices for genetically enhanced seeds that offer built-in climate resilience, pest resistance, and higher yield potential. Bayer’s ability to grow its soybean and corn segments amidst broader macroeconomic uncertainty validates the company’s R&D investments and its strategic pivot toward biologicals, digital farming tools, and advanced seed genetics.
Official Statements and Leadership Perspectives
Bayer’s executive team addressed investors, analysts, and stakeholders with a blend of candor regarding immediate operational hurdles and resolute confidence in the company’s multi-year strategic roadmap.
Chief Executive Bill Anderson did not shy away from the structural headwinds facing the division. During his opening remarks, Anderson stated:
"Our Core Crop Protection business is down on the year due to expected portfolio exits, regulatory impacts, and increased generic pressure."
He stressed, however, that these intentional portfolio adjustments are a necessary part of a broader corporate cleanup designed to eliminate low-margin drag and refocus the company on high-value, high-margin technological solutions.
Chief Financial Officer Judith Hartmann elaborated on the company’s fiscal agility, highlighting how internal cost-containment measures managed to protect profitability despite top-line revenue pressures. Hartmann noted:
"We have taken targeted actions to address challenging market conditions, supporting volume growth in Latin America in Q3."
Her commentary underscored that disciplined capital allocation and localized inventory management were instrumental in preserving the division’s impressive 24.6% EBITDA margin.
Crop Science President Rodrigo Santos provided granular operational insights during the post-earnings analyst Q&A session. Santos explained how localized weather extremes dictated agronomic behavior:
"Unusually hot and dry conditions in Europe and Asia had a particularly noticeable impact on fungicide demand, as dry fields drastically reduced fungal spore proliferation and rendered prophylactic spraying economically unviable for local growers."
Furthermore, Santos addressed the shadow of ongoing legal challenges, specifically mentioning that Bayer remains firmly focused on achieving "significant containment" regarding legacy Roundup litigation via proposed structured settlement pathways. However, he was quick to redirect stakeholder focus back to the core operational execution, emphasizing that regulatory navigation, climate adaptation, and market share retention in seeds remain the true determinants of the division’s long-term enterprise value.
Future Outlook: Navigating 2027 and Beyond
As the 2026 agricultural season draws to a close, Bayer’s leadership is actively plotting its strategic course for 2027. The upcoming fiscal year presents a complex matrix of persistent market challenges and emerging technological opportunities.
Anticipated Headwinds and Market Realities
Crop Science President Rodrigo Santos explicitly warned that the global agricultural market will likely remain challenging heading into 2027. Several macro-environmental factors underpin this cautious outlook:
- Weather Volatility: The increasing frequency and unpredictability of climate anomalies—ranging from El Niño transitions to persistent multi-year droughts in key breadbasket regions—will continue to disrupt traditional input application cycles.
- Farmer Profitability Constraints: Persistently high input costs relative to fluctuating crop commodity prices mean growers will likely maintain a conservative approach to capital expenditures, favoring cost-effective generic inputs where proprietary performance premiums are not immediately obvious.
- Regulatory Compression: Stricter environmental mandates, particularly within the European Union, will continue to restrict the use of conventional chemical active ingredients, necessitating accelerated R&D investments in biological crop protection and sustainable alternatives.
The Turnaround Blueprint and Strategic Growth Pillars
Despite these headwinds, Bayer maintains that its overarching five-year Crop Science turnaround plan is fully on schedule. The 17.4% year-to-date expansion in EBITDA before special items proves that aggressive cost-cutting, manufacturing footprint optimization, and administrative streamlining are effectively insulating the business from cyclical downturns.
Moving into 2027, Bayer plans to double down on several core growth pillars:
- Latin American Expansion: Building upon the robust momentum established this season, the company will treat Latin America as the anchor region for volume growth, scaling distribution networks for advanced soybean and corn traits.
- Digital and Biological Integration: Accelerating the commercialization of next-generation biological crop protection tools and digital agronomy platforms to help farmers navigate regulatory restrictions and climate stress.
- Portfolio Disciplining: Continuing to prune underperforming chemical assets while aggressively protecting high-margin proprietary seed portfolios from generic erosion through enhanced trait efficacy and intellectual property defense.
Ultimately, Bayer’s third-quarter results reflect a transitional phase for its agricultural empire. By successfully leveraging regional bright spots like Latin America and aggressively executing internal restructuring programs, the company is positioning itself to weather near-term climatic and regulatory storms while securing long-term dominance in the evolving global ag-tech sector.