
Executive Overview
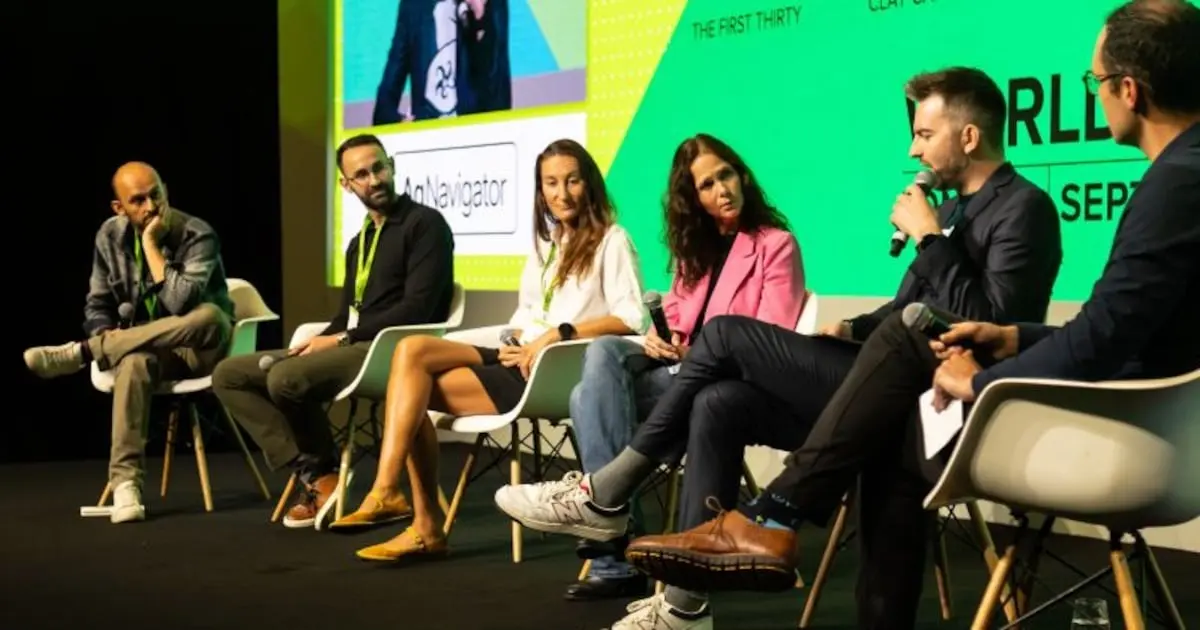
There was no shortage of visionary proposals, sophisticated algorithms, or molecular breakthroughs at this year’s World Agri-Tech Innovation Summit in London. Yet, walking the exhibition halls and listening to the plenary panels, one prevailing sentiment quickly eclipsed the traditional industry hype: the era of "shiny-new-object syndrome" in agricultural technology has officially come to an end.
For years, venture capital and corporate research departments chased hyper-novelty—proposing futuristic utopian visions of autonomous fleets operating in idealized vacuums or synthetic-heavy platforms detached from the gritty realities of agrarian economics. At this year’s gathering, however, the industry’s collective gaze shifted firmly back to the fundamentals. Global agriculture is presently grappling with an unprecedented confluence of systemic pressures: escalating climate volatility, acute water scarcity, soaring input costs, and mounting, stubborn resistance among pests and pathogens.
Farmers do not need more laboratory-bound novelties that look extraordinary in a PowerPoint presentation. They urgently need tools that work reliably day in and day out, integrate smoothly into existing machinery and crop-management systems, and, crucially, make unassailable economic sense.
While the underlying technology is largely ready—spanning advanced artificial intelligence, precision gene editing, next-generation biologicals, and regenerative finance models—the overarching bottleneck has shifted. The central question for the global agtech sector is no longer whether we can invent the solution; it is whether our regulatory frameworks, investment pipelines, and commercial business models can keep pace with real-world deployment.
Detailed Chronology & Narrative Breakdown
The Regulatory Balancing Act: Gene Editing Takes Center Stage
Gene editing emerged as one of the summit’s most intensely debated talking points, catalyzed by an increasingly favorable regulatory environment on both sides of the English Channel. The debate, however, quickly segued from scientific potential to geopolitical and trade friction.
The United Kingdom—specifically England—has moved furthest and fastest on this front, establishing a distinct regulatory regime for precision-bred organisms. This forward-looking framework covers genetic changes that could theoretically have been achieved through conventional, time-consuming breeding techniques. Meanwhile, across the water, the European Union is heading in a similarly progressive direction through its evolving rules for New Genomic Techniques (NGTs), though it maintains a more prescriptive, bureaucratic framework.
This divergence has created a thorny diplomatic puzzle. As the UK and the EU negotiate a new sanitary and phytosanitary (SPS) agreement, Great Britain’s early-mover advantage threatens to complicate matters. The proposed deal aims to see Great Britain dynamically align with major swathes of EU agrifood regulation in exchange for substantially reduced trade friction at the border. Precisely where that leaves England’s independent approach to agricultural biotechnology remains an unresolved, high-stakes detail.
Addressing the summit, the UK’s newly appointed farming secretary, Steven Morgan—the third minister to hold the post in just two years—pledged to protect the nation’s regulatory freedoms concerning agricultural biotechnology. The frequent turnover of agricultural ministers amid ongoing UK political instability serves as a backdrop to this tension, but the core economic dilemma remains stark: Can the UK secure frictionless agrifood trade with its largest continental neighbor without surrendering the regulatory flexibility it believes will give its domestic gene-editing sector a decisive global competitive edge?
The Biologicals Bottleneck
Gene editing is increasingly intersecting with other high-growth segments of agtech, including artificial intelligence, biological crop protection, regenerative agriculture systems, and sophisticated agri-finance structures. Yet, unbridled enthusiasm for biologicals was consistently tempered by a familiar, frustrating refrain: Europe’s regulatory apparatus remains poorly calibrated for natural, living inputs.
"If Europe can move towards a science-based, risk-based regulatory system that allows biologicals, natural products, and other solutions derived from nature to follow a more streamlined process, I think we will see that technology flowing and growing at a faster pace," Corteva’s Tom Greene told delegates during a packed panel session.
The biological opportunity is immense, driven by chemical resistance and consumer demand for reduced synthetic residues. However, the regulatory friction continues to choke the pipeline, leaving valuable environmental solutions trapped in protracted approval loops.
Big Ag’s Open-Door Policy
Amid broader macroeconomic headwinds and a prolonged squeeze in venture capital funding, a vital message emerged for early-stage start-ups: major agribusiness conglomerates are finally opening their doors to external innovation.
Faced with identical macro-level threats, major players are increasingly abandoning the insular, "not-invented-here" R&D philosophy that historically dominated multinational boardrooms. Instead, they are actively hunting for the best technologies wherever they originate.
This shift in corporate strategy is already materializing in high-profile partnerships:
- Corteva: Through its forthcoming Vylor business, Corteva has partnered with Belgian biotech firm Rainbow Crops to co-develop climate-resilient corn variants leveraging artificial intelligence and multiplex gene editing.
- Bayer: The life sciences giant is heavily backing Robigo, an innovative start-up deploying engineered microbes, RNA interference, and CRISPR platforms for next-generation crop protection.
- Syngenta: Beyond announcing major proprietary breakthroughs from its internal laboratories—such as claiming the first new mode of action in biologicals in two decades via microRNA technology—Syngenta has forged targeted external alliances with specialized firms including Amoéba and Groundwork BioAg.
For cash-strapped start-ups navigating a hostile fundraising climate, corporate backing provides a vital lifeline. Interestingly, however, corporate investors noted that they are not always looking for the newest, unproven invention. Several industry insiders revealed that some of the most attractive targets on their radar are "old start-ups"—technologies that have been around for several years but have recently undergone strategic management overhauls, rendering them commercially viable and market-ready. Perseverance, product-market fit, and operational execution are rapidly displacing mere novelty as the keys to survival.
Supporting Context & Metrics: The Reality of On-Farm Integration
A persistent theme throughout the London summit was the humbling reality that technically superior products do not automatically win market share. A scientific breakthrough can post stellar performance metrics in controlled laboratory trials, yet still fail miserably if it does not fit an individual farmer’s unique operation, cash-flow constraints, and appetite for operational risk.
The Power of the Agronomic Middlemen
Time and again, speakers pointed to local agricultural distributors, farm advisors, and agronomists as agtech’s unsung heroes. Too much historical venture capital has been poured exclusively into product-level R&D, while critically underfunding integration, local soil validation, and distribution channels.
When a novel product hits the chaotic, variable conditions of a working farm—battling unpredictable weather, machinery incompatibilities, and labor shortages—its theoretical value can evaporate overnight. Consequently, the true market winners of the next decade will likely not be the companies making the boldest headline claims, but rather those that relentlessly simplify complexity and guarantee dependable performance under messy, real-world conditions.
Official Statements & Industry Perspectives
The structural imbalances plaguing the agricultural transition were brought into sharp focus by leading policymakers and industry executives, who interrogated the fundamental question: Who pays for the green transition?
"When the transition is not supported, all the costs, all the burden, directly goes on the shoulders of the farmers."
— Bengü Özge Şerifoğlu, Agricultural Economist and Sustainability Strategist
Throughout discussions spanning carbon markets, crop insurance, and climate resilience, speakers returned to a glaring structural flaw: farmers are routinely expected to make heavy, upfront investments in sustainable infrastructure while operating on razor-thin margins. Meanwhile, the financial and reputational value generated by these sustainable practices frequently accrues further up the supply chain—benefiting food processors, major retailers, and corporate sustainability ledger-keepers.
Echoing this warning, former UK Environment Secretary George Eustice argued during a keynote session that existing agricultural margins are fundamentally incapable of supporting the scale of capital expenditure required for long-term climate resilience.
"I personally think that we’re going to have to recognise that there’s a need for a structural increase in food prices over the next twenty or thirty years. The world has enjoyed cheap food for too long."
— George Eustice, Former UK Environment Secretary
While the summit did not arrive at a neat, universal consensus on how to finance this massive transition, a profound philosophical shift was palpable. A voluntary, purely farmer-funded sustainability transition is no longer mathematically viable. Moving forward, the industry must pivot toward sophisticated blended finance models, supply-chain insetting, and shared-risk frameworks that distribute financial liability fairly across banks, insurance syndicates, multinational agribusinesses, and primary producers.
Future Outlook: The Next Phase of Agtech Deployment
As the 2026 World Agri-Tech Innovation Summit drew to a close, the consensus was clear: the primary challenge facing the agricultural technology sector is no longer inventing another clever piece of software or splicing another gene.
Artificial intelligence, precision gene editing, biological crop inputs, and advanced regenerative farming metrics have profoundly expanded the boundaries of what is technically possible in agronomy. Major agribusinesses are increasingly receptive to external partnerships, and start-up innovators continue to generate high-potential intellectual property.
However, farmers facing deepening climate chaos and unrelenting margin pressure cannot be expected to shoulder the financial and operational risk of deploying these tools in isolation.
Agtech has no shortage of brilliant technology. Its defining test over the coming decade will be building the robust regulatory, financial, and commercial machinery required to move those innovations out of the laboratory and reliably onto the farm.