
Executive Overview
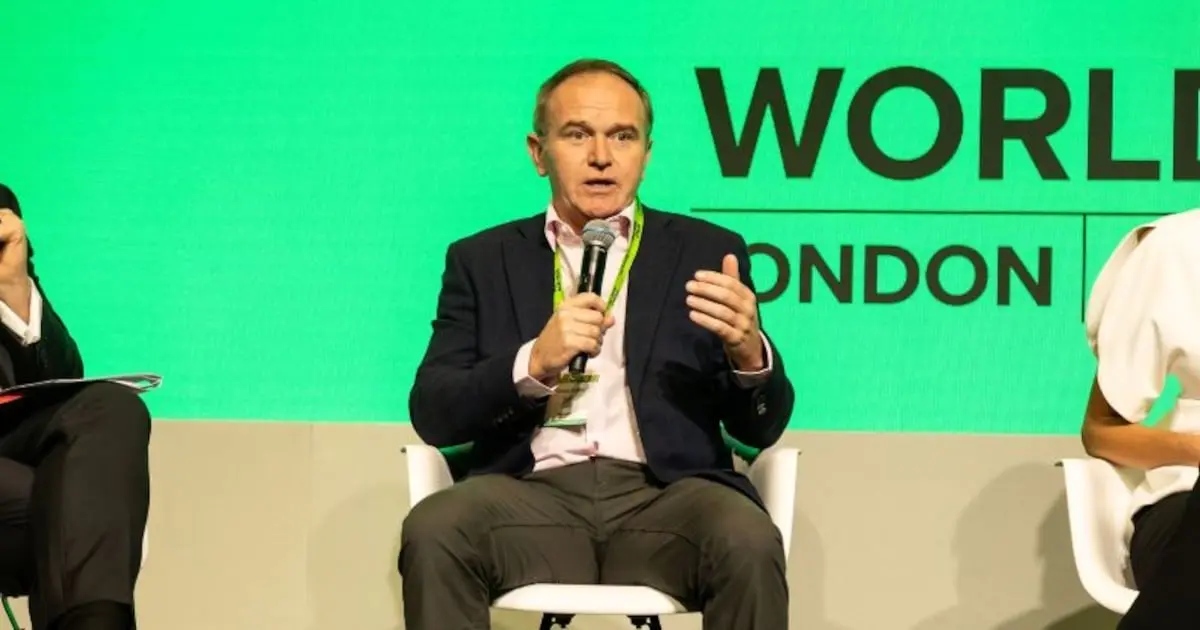
The global agricultural landscape stands at a critical juncture, defined by compounding environmental pressures, shifting geopolitical trade alignments, and a widening chasm between rapid technological innovation and sclerotic regulatory frameworks. Speaking exclusively to AgNavigator at the prestigious World Agri-Tech Innovation Summit in London, George Eustice, former UK government official and current managing director of Penroath consultancy, delivered a stark assessment of the realities facing the modern food supply chain.
According to Eustice, the confluence of escalating climate volatility, mounting production risks, and the urgent economic necessity for intensive on-farm investments means that structurally higher food prices are no longer a temporary anomaly—they are an inevitable economic reality of the 21st century. As traditional breadbaskets, particularly in the Mediterranean basin, face severe and chronic environmental degradation, global agricultural output is increasingly compromised.
Compounding these macroeconomic headwinds are regulatory bottlenecks that threaten to stifle agtech innovation across Europe and the United Kingdom. While the UK has championed a progressive, risk-based approach to gene editing following its departure from the European Union, the specter of a future Sanitary and Phytosanitary (SPS) alignment agreement with Brussels casts a long shadow over Britain’s hard-won regulatory freedoms. Simultaneously, exorbitant authorization timelines—stretching up to a decade or more for critical innovations like biopesticides—are actively driving agile agtech small and medium-sized enterprises (SMEs) away from European markets in favor of the more commercially welcoming ecosystems of the United States and South America.
This comprehensive report examines the structural drivers behind impending global food inflation, evaluates the high-stakes debate surrounding post-Brexit regulatory divergence versus EU alignment, and highlights the urgent calls for regulatory decentralization to prevent a mass exodus of agricultural technology talent.
Detailed Chronology: Perspectives from the World Agri-Tech Innovation Summit
The dialogues at the World Agri-Tech Innovation Summit in London encapsulated the urgency felt by policymakers, investors, and industry leaders alike. The timeline of key disclosures and policy positions articulated during the summit underscores the tightening margins within the global agricultural sector:
- Early Conference Proceedings: Opening panels at the summit focused heavily on the necessity of "getting back to fundamentals," with venture capitalists and agtech developers acknowledging that speculative capital must now give way to pragmatic technologies that directly address on-farm operational risks.
- Ministerial Assurances: UK Farming Minister Stephen Morgan addressed delegates, attempting to soothe anxieties surrounding ongoing negotiations with the European Union. Morgan asserted that the British government remains firmly committed to protecting the nation’s sovereign right to pursue agricultural innovation, even as exploratory talks regarding a potential SPS framework agreement progress.
- The Eustice Intervention: Later in the proceedings, George Eustice took to the stage to offer a pragmatic—and sobering—perspective. Bridging his experience in public office with his current role at Penroath consultancy, Eustice highlighted the direct link between global climate shocks, the economic fragility of supply chains, and inevitable consumer price increases.
- Regulatory Warnings: Transitioning from macroeconomics to policy, Eustice pinpointed the dual threats facing European agtech: the risk of the UK compromising its gene-editing advantage through an overly restrictive SPS treaty, and the systemic failure of the EU’s regulatory machinery, which continues to hemorrhage innovative start-ups to foreign jurisdictions.
Supporting Context & Metrics: The Anatomy of Food Inflation and Agtech Flight
To fully understand Eustice’s warnings regarding long-term food inflation and agricultural stagnation, one must examine the underlying structural pressures currently redefining the economics of food production.
The Mediterranean Squeeze and Global Supply Shocks
The agricultural paradigm is shifting away from historical norms. For decades, the UK and Northern Europe have relied heavily on Mediterranean agricultural powerhouses—including Spain, Italy, Greece, and parts of North Africa—to supply fresh fruits, vegetables, and specialized produce during off-seasons. However, these regions are ground zero for the climate crisis.
Chronic droughts, acute water scarcity, record-breaking heatwaves, and soil salinization have severely degraded arable land across Southern Europe. As Eustice noted during his summit address, the basic laws of supply and demand dictate that as these vital production hubs continuously struggle to meet historical output levels, global inventories will shrink. When supply contracts in the face of steady or growing demand, structural price inflation becomes the market’s primary clearing mechanism.
The Cost of Resilience
Beyond basic yield deficits, farming in a volatile climate requires massive capital expenditure. Farmers can no longer rely on traditional seasonal predictability; instead, they must invest heavily in climate-resilient infrastructure. This includes:
- Precision irrigation and water-recycling systems to combat drought.
- Controlled-environment agriculture (CEA) and vertical farming infrastructure.
- Advanced soil health management technologies and biological inputs.
However, these technologies require robust capital. Eustice emphasizes that if farmers are expected to absorb the financial risks of transitioning to climate-smart agriculture, market prices must adequately reflect these costs, ensuring sufficient returns to justify long-term on-farm investments.
The Regulatory Exodus: A Ten-Year Horizon for Approvals
While climate change threatens the physical output of food, regulatory friction threatens the tools required to protect it. Agtech SMEs—particularly those specializing in sustainable biologicals, biopesticides, and climate-adapted seed varieties—face a grueling pathway to commercialization within the European regulatory sphere.
According to industry data highlighted at the summit, securing regulatory authorization for novel biological products in Europe can routinely take between 10 and 12 years. This protracted timeline introduces crippling financial uncertainty for early-stage companies that lack the multi-million-dollar war chests of legacy multinational agrochemical corporations. Consequently, a quiet brain-drain and capital flight are underway. Innovative agtech firms are voting with their feet, bypassing European markets entirely to seek commercialization pathways in the United States and South America, where regulatory frameworks—while rigorous—offer more predictable and accelerated timelines.
Official Statements and Policy Debates
The tension between regulatory harmonization and sovereign innovation formed a cornerstone of the discussions in London, particularly concerning the future of gene editing and biotechnology.
The UK’s Gene-Editing Crossroads
Following its departure from the European Union, the United Kingdom adopted a progressive, risk-based regulatory framework regarding Precision Breeding (gene editing). Unlike traditional genetically modified organism (GMO) regulations that focus strictly on the process of genetic alteration, the UK’s approach focuses on the trait itself—specifically whether the genetic changes could have occurred naturally through traditional breeding methods. This framework allows many gene-edited crops to clear regulatory hurdles significantly faster than in the EU, positioning the UK as a potential global hub for agricultural biotechnology.
However, this competitive advantage is now imperiled by diplomatic realities. The current Labour government’s pursuit of a closer sanitary and phytosanitary (SPS) agreement with the European Union has ignited fierce debate. While Farming Minister Stephen Morgan sought to reassure the agricultural sector that research and development competencies would remain strictly domestic, industry veterans remain skeptical.
George Eustice cautioned that the devil will lie in the implementation details:
"The key line that I took out of it really was him saying that although they’re in discussions on an SPS agreement, research and development on things like gene editing and other sectors will remain a UK competence and I think that’s important reassurance… I think the big question is whether then we see that approach apply equally to the cultivation of gene-edited crops and that’s the really important thing we need to retain."
Eustice lauded the UK’s post-Brexit legislative trajectory, describing the gene-editing reforms as "really quite groundbreaking." He expressed hope that the European Union might eventually look across the Channel, recognize the administrative failures of its own centralized system, and reform its rules accordingly.
A Plea for Brussels: Decentralization or Stagnation
Failing a wholesale structural overhaul of EU-wide agricultural policy, Eustice offered a pragmatic alternative: regulatory subsidiarity. Rather than forcing a cumbersome, one-size-fits-all consensus across all 27 member states—a process frequently paralyzed by political friction and ideological division—Brussels should grant individual member states the autonomy to opt into progressive agricultural technologies.
"If this is too difficult for us to get a sensible consensus on, then open the door to national decision-making in these areas," Eustice argued, pointing to technologies ranging from gene-edited crops to advanced biostimulants and specialized fertilizers. By allowing willing nations to embrace innovation independently, Europe could prevent the total stagnation of its agricultural sector.
Future Outlook: Navigating the New Agrarian Era
As the agricultural sector looks toward the remainder of the decade and beyond, the trajectories outlined at the World Agri-Tech Innovation Summit point toward a profoundly transformed industry.
- Sustained Consumer Price Pressures: Structural food inflation is poised to remain a persistent feature of global economies. As climate change inflicts structural damage on Southern European and global breadbaskets, supply chain resilience will command a permanent premium. Consumers must adjust to an era where cheap, abundant food is increasingly replaced by climate-adjusted pricing models that reflect the true cost of production and environmental risk.
- The Geopolitical Regulatory Battleground: The UK government faces a delicate balancing act. Maintaining regulatory independence in biotechnology—particularly gene editing—is vital if the nation is to retain its hard-won status as an agtech incubator. Should a future SPS agreement with the EU erode this freedom for the sake of friction-free trade in traditional commodities, Britain risks sacrificing its long-term technological edge for short-term administrative convenience.
- The Risk of European Marginalization: Unless Brussels radically streamlines its authorization pathways for biopesticides and gene-edited innovations—or pivots toward national decision-making flexibility—Europe risks accelerating the flight of its brightest agtech minds. The global race for agricultural sustainability will not wait for bureaucratic consensus; capital and innovation will naturally flow to the jurisdictions that reward speed, science, and adaptability.
Editor’s Note: The full on-camera interview with George Eustice, along with comprehensive panel discussions from industry leaders, will be featured in AgNavigator’s upcoming "World Agri-Tech Unwrapped" webinar on November 4. Industry professionals and stakeholders can register for free access on the AgNavigator platform.